Two Signatures, One Student: The Hidden Cost of Borrowing Side by Side

Photo by Photo by Vitaly Gariev on Unsplash on Unsplash
The Household That Borrowed Twice
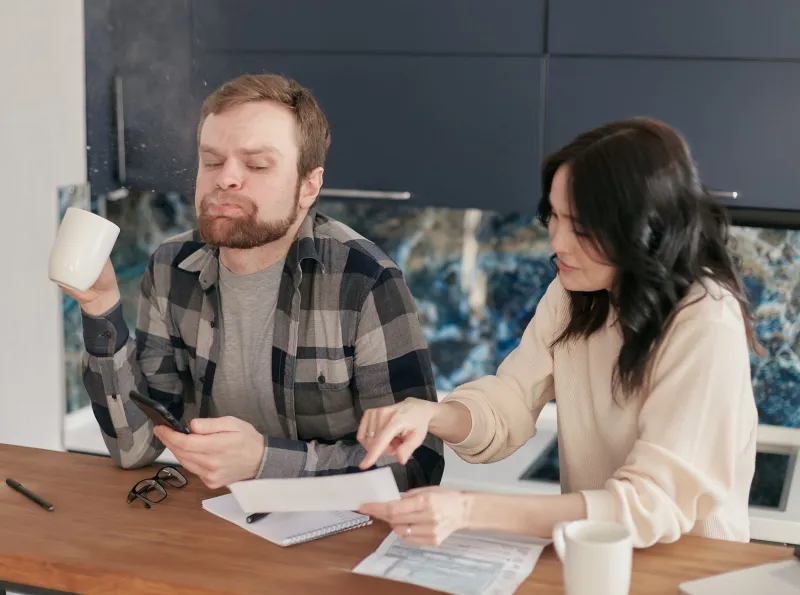
Consider a common scenario: a student's fall tuition bill arrives at $28,000 after aid. One parent, perhaps the one who handles the bursar portal, accepts a Parent PLUS loan for the full gap. Months later, the other parent — worried about the 8-plus percent federal rate — pulls $20,000 from a 401(k) and takes out a private education loan through a credit union to cover spring. Neither decision is reckless in isolation. Together, they can leave a family servicing three obligations, in three names, with three different rulebooks, and no single document showing the true cost of one degree.
This is the parallel borrowing problem, and it thrives precisely because education debt is usually researched and signed by individuals, not households.
Why the Exposure Doubles Quietly
Parent borrowing rarely happens in one sitting. Tuition bills arrive semester by semester, and each one invites a fresh decision. A couple may divide duties — one manages cash flow, the other handles investments — and each acts rationally within their own lane. The result:
- Overlapping principal. Two loans sized independently can collectively exceed what one optimally structured loan would have required.
- Mismatched terms. A Parent PLUS loan carries origination fees and federal protections; a private loan may offer a lower rate but none of the safety net; a retirement withdrawal carries neither interest nor repayment schedule — just permanent opportunity cost.
- No unified payoff strategy. Without coordination, extra payments get scattered across balances instead of targeted at the most expensive dollar.
A Framework: Four Questions Before Anyone Signs
Families can prevent duplication with a short joint review before each academic year. Ask:
1. Who is the cheapest borrower in the room? Compare the all-in cost — rate plus fees — of Parent PLUS versus private loans in each parent's name. A parent with strong credit may qualify for a private rate well below the federal parent rate, while a parent with thinner credit may find Parent PLUS the only realistic option.
2. What protections matter to this family? Parent PLUS loans offer income-contingent consolidation paths and discharge upon death or total disability. Private loans may not. If job security or health is uncertain, the federal option's flexibility has real, if hard-to-price, value.
3. Whose retirement are we really spending? A 401(k) withdrawal before age 59½ typically triggers income tax plus a 10 percent penalty, and it permanently removes tax-deferred growth. If retirement funds must bridge a gap, treat it as a last-dollar decision made by both spouses — not a quiet unilateral one.
4. What are the tax and estate implications of the name on the loan? Interest on parent education debt is generally not deductible, but loan balances affect each borrower differently: they can shape debt-to-income ratios for future borrowing, and in community property states, marital exposure may be broader than either spouse assumes. For families with possible forgiveness-eligible employment or future refinancing plans, whose name carries the debt deserves deliberate thought.
Building the Single-Ledger Household
The remedy is administrative, not exotic. Create one shared document — a spreadsheet suffices — listing every education obligation by lender, balance, rate, fee, term, and borrower. Update it each semester before the next borrowing decision. Then apply a simple hierarchy: exhaust federal student loans in the student's name first, choose the cheapest parent option for the remainder, and reserve retirement assets for genuine emergencies.
Finally, hold a five-minute conversation before each disbursement: "Is this the best dollar we can borrow, in the best name, at the best rate available to us right now?" Families who ask it together rarely find themselves paying twice for the same diploma.