From Spare Change to Semester Bills: Auditing the New Wave of 529-Linked Payment Apps
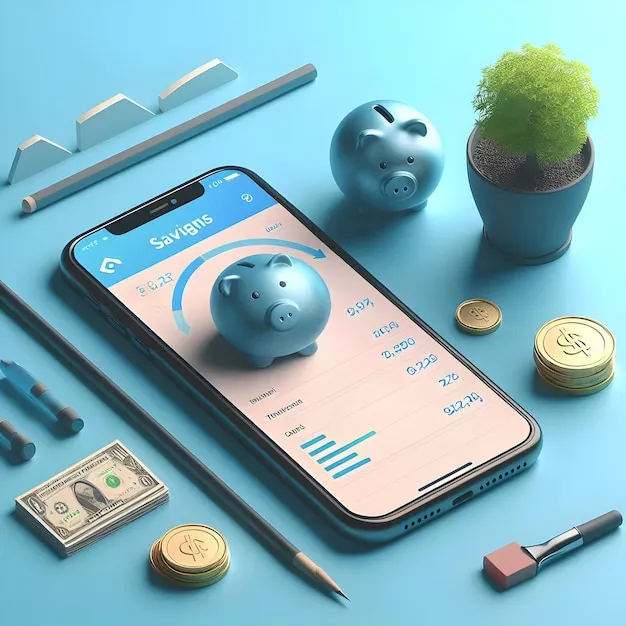
Photo: smartphone banking app college savings tuition payment, via img.freepik.com
For decades, the 529 plan has been a passive instrument: money goes in, markets do their work, and eighteen years later a family draws down the balance against a bursar's bill. That model assumed a level of household organization that many families simply cannot sustain. A new generation of apps is betting on that weakness — and in some cases, on parental anxiety itself.
The pitch is seductive in its simplicity. Link your debit card, let the app sweep round-up change into a 529, then flip a switch so the accumulated savings automatically satisfy tuition installments when they come due. Saving and paying become one continuous pipeline, with no spreadsheets, no transfer forms, and no November scramble. But behind that clean interface sits a patchwork of fee schedules, account structures, and integrations of very different quality.
What These Apps Actually Do
Strip away the marketing and most platforms in this space perform some combination of three functions. The first is micro-saving: round-up transactions, recurring weekly deposits, or gift registries that funnel birthday money into a college account. The second is investment management — typically a 529 held at a partner program with an age-based portfolio selected by the app. The third, and newest, is payment routing: authorizing the platform to remit funds directly to a school's bursar office on a schedule.
The first two functions have precedents. Round-up investing is a mature category, and state 529 programs have long partnered with third-party administrators. It is the third function that changes the equation, because it collapses the wall between saving for college and paying for it — and that wall existed for a reason.
Where the Integrations Genuinely Help
The strongest case for these platforms is behavioral. Families who automate contributions save more than families who rely on willpower; this is one of the most replicated findings in personal finance research. An app that sweeps $40 a month without friction will, over a decade, produce a balance that a well-intentioned manual saver often never gets around to building.
Direct-to-bursar payment also solves a real logistical problem. Many 529 plans require families to request a withdrawal, wait for a check or ACH transfer, and then reconcile the disbursement with the school's billing cycle — a process that can stretch past tuition deadlines. Platforms that remit on schedule, and that generate the tax documentation needed to match qualified expenses to withdrawals, remove a genuine administrative burden.
For middle-income families staring down a predictable gap — say, $3,000 to $5,000 per semester after aid and federal loans — a pipeline that reliably delivers a few hundred dollars a month toward the bill can measurably reduce private borrowing. At a 9% rate, every $4,000 of tuition financed from savings instead of a private loan saves roughly $1,300 in interest over a standard repayment term.
Where the Fees Hide
The weaker versions of this model deserve scrutiny. Some platforms layer an asset-based fee on top of the underlying 529 program's expense ratio, effectively charging parents twice for a portfolio they could hold directly through their state's plan. Others monetize the payment function itself — a per-transaction fee for remitting tuition, or premium tiers gated behind monthly subscriptions that only make sense for balances well above what most round-up savers accumulate.
The math is unforgiving. A round-up feature that captures $25 a month cannot justify a $6 monthly subscription; the fee would consume nearly a quarter of the savings before a single dollar reached the market. Families evaluating these apps should run the same test any advisor would: total annual cost of the platform plus the underlying plan, expressed as a percentage of expected contributions. If that figure exceeds roughly 0.5% to 0.75%, a direct enrollment in a low-cost state 529 — most states offer direct-sold plans with expense ratios below 0.25% — is almost certainly the better vehicle.
There is also a structural caveat: many of these apps route savings into 529s administered by a single partner program, not the saver's home-state plan. For residents of states offering meaningful tax deductions on contributions — New York, Michigan, Colorado, and roughly thirty others — abandoning the in-state plan can forfeit a deduction worth hundreds of dollars a year.
Questions to Ask Before Linking an Account
Families considering one of these platforms should treat the evaluation like any other financial product. Start with the fee stack: what does the app charge, what does the underlying 529 charge, and is there a transaction fee on payments to the bursar? Confirm the 529 program itself — its name, its manager, and whether your state's deduction applies. Ask what happens if you stop paying for the subscription: does the money remain invested, and can you withdraw directly from the plan without the app as an intermediary?
Finally, verify the payment integration's reliability. A platform that remits late, or that cannot document which withdrawals correspond to which qualified expenses, creates problems at tax time that no round-up feature can offset. Under federal rules, withdrawals must match qualified education expenses in the same tax year, and the recordkeeping burden ultimately falls on the family.
The Bottom Line
The automation these apps offer is real, and for households that have struggled to save consistently, a friction-free pipeline from spare change to tuition bill can shift hundreds of dollars per semester away from debt. But the technology is not magic, and it is not free. The families who benefit will be those who read the fee schedule as carefully as the marketing page — and who recognize that the cheapest 529-linked payment system is often the state plan, an automatic contribution, and a calendar reminder when the bursar's bill arrives.